
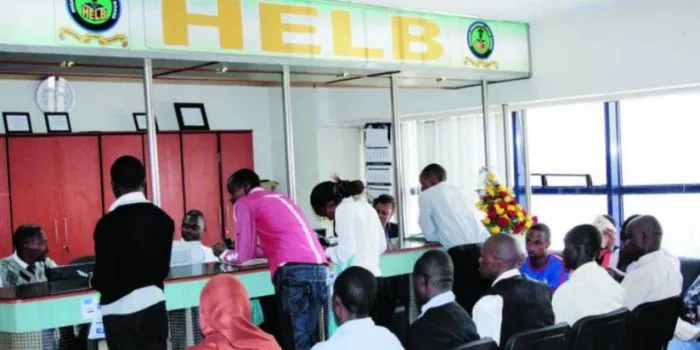
HELB encourages unemployed and self-employed borrowers to make consistent, affordable loan repayments.
HELB urges unemployed and self-employed borrowers to make affordable payments, recommending a Ksh1,500 monthly baseline for informal and low-income earners.
HELB loan repayment must begin within one year of completing studies, even for graduates without formal employment. The Higher Education Loans Board says the requirement also covers self-employed borrowers and those running businesses.
In a notice dated November 11, the board urged unemployed and self-employed beneficiaries to start with affordable amounts. It encouraged borrowers to maintain consistent payments as they work towards clearing their student loans.
For informal and low-income earners, HELB recommends a monthly baseline of Ksh1,500. However, that recommendation does not mean every borrower will repay the same amount.
HELB loan repayment guidance for informal earners
The board encouraged borrowers earning through small businesses and freelance work to make manageable payments. Its message covered activities such as selling clothes, running kiosks and freelancing, alongside other forms of self-employment.
Rather than waiting for formal employment, beneficiaries should begin servicing their loans within the stated period. HELB also linked consistent repayments to helping fund the next group of students seeking higher education support.
Beneficiaries can also make voluntary payments before completing their studies or after graduation to reduce their outstanding balances. For those repaying gradually, the recommended Ksh1,500 monthly baseline provides a starting point for regular payments.
Why some borrowers pay higher monthly amounts
Some borrowers, particularly those in formal employment, report monthly payments of up to Ksh5,000. HELB can recommend higher instalments depending on a beneficiary’s loan balance and repayment circumstances.
For example, large undergraduate and postgraduate loans can require monthly deductions of Ksh4,000 to Ksh6,000. Those amounts may reflect the standard four per cent reducing-balance interest calculation over a fixed repayment period.
Meanwhile, borrowers who spent years in default may face higher deductions when they begin paying. HELB can direct an employer to increase deductions to cover missed payments and accumulated penalties.
Borrowers can also choose to pay more voluntarily to clear their debt sooner. Because HELB calculates interest on a reducing balance, larger payments reduce the outstanding principal and total interest over time.