
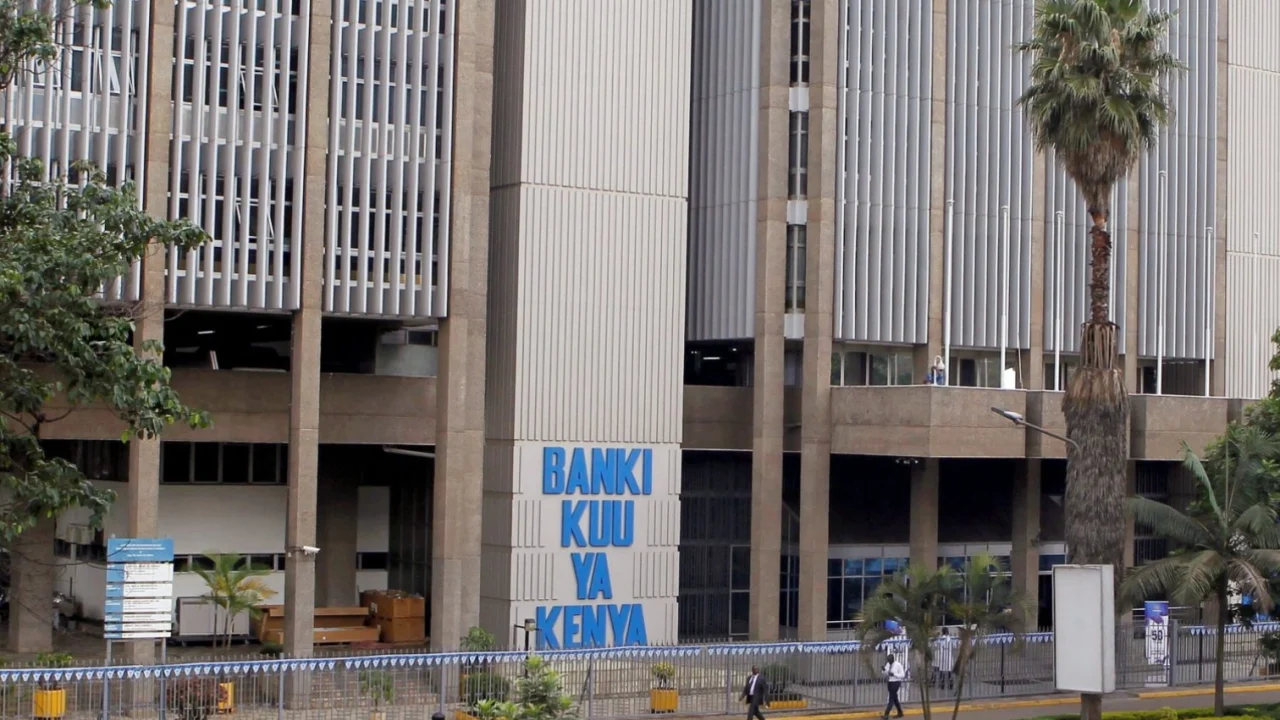
The Central Bank of Kenya (CBK) has penalised 33 commercial banks over breaches linked to loan pricing, marking a major regulatory crackdown in the banking sector.
The penalties followed targeted inspections conducted in 2025 to assess how banks were implementing the Risk-Based Credit Pricing Model (RBCPM).
According to CBK’s 2025 Banking Supervision Report, all commercial banks were assessed. Three banks were fully compliant, while two others faced administrative action.
Banks Failed to Pass on Rate Cuts
The crackdown comes after the CBK repeatedly pushed lenders to reduce borrowing costs following cuts to the Central Bank Rate (CBR).
Between August 2024 and August 2025, the CBR fell from 13 percent to 9.5 percent. However, the regulator found that many banks did not fully reflect the lower benchmark rate in their lending rates.
The CBK report shows that 35 banks had breached various provisions of the Banking Act or Prudential Guidelines by December 31, 2025. That figure compares with 11 banks recorded in the previous year.
Other Banking Violations
The inspections also uncovered other regulatory breaches. Ten banks violated the 25 percent single obligor limit, which restricts lending exposure to one borrower or related group.
Meanwhile, seven banks failed to maintain the mandatory KSh3 billion minimum core capital. Other breaches involved insider lending, capital adequacy and prohibited business activities.
New Loan Pricing Model
The CBK introduced a revised RBCPM to improve transparency in loan pricing. Under the framework, variable-rate loans are linked to KESONIA, with the bank adding a premium based on lending costs and borrower risk.
The framework took effect for new variable-rate loans from September 1, 2025. Existing variable-rate loans transitioned by February 28, 2026.
What Borrowers Should Know
The crackdown comes as average commercial bank lending rates continue to fall. CBK data shows the average lending rate stood at 14.39 percent in July 2026, down from higher levels recorded in 2025.
For borrowers, the changes mean loan pricing should increasingly reflect the regulator’s benchmark framework. However, individual loan rates can still vary depending on the bank’s pricing premium, borrower risk and applicable fees.